Modernizing Insurance Claims Intake with Voice AI and Real-Time Fraud Scoring
USMICRO established an ODC-led claims modernization model that converted natural policyholder conversations into structured FNOL records, automated document and workflow orchestration, and introduced real-time fraud-risk scoring earlier in the claims lifecycle.
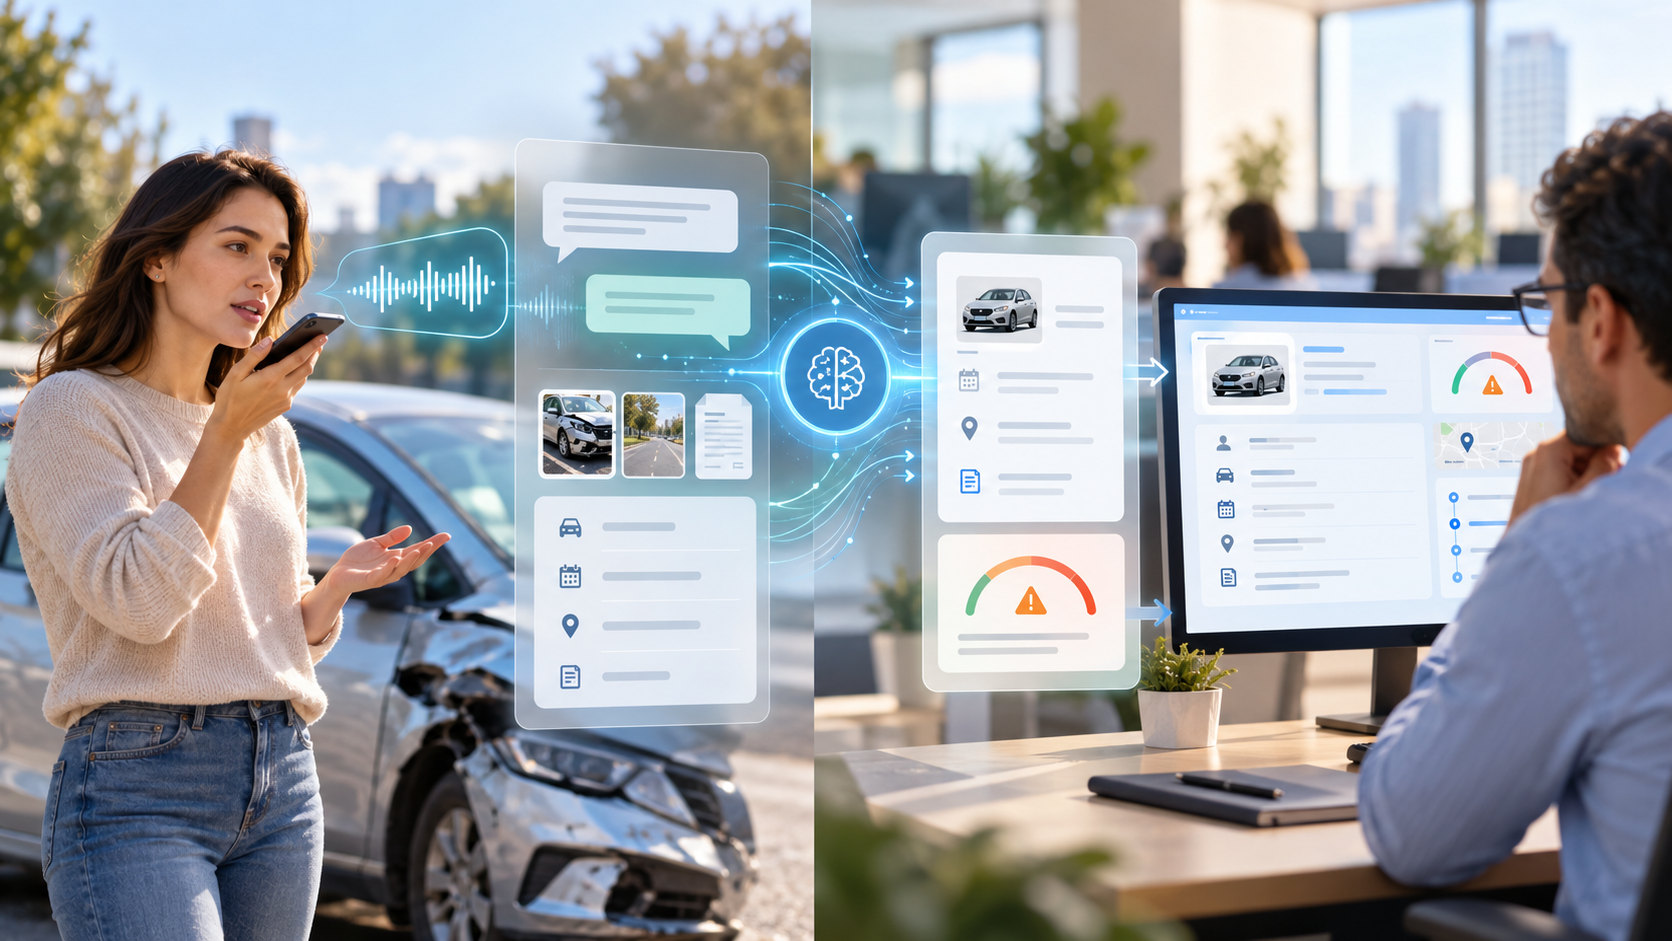
What needed to change.
The insurer’s First Notice of Loss process depended heavily on rigid forms, call-centre scripts and manually captured claim information.
Policyholders experiencing an accident or loss were required to translate an often complex real-world event into predetermined fields while claims personnel simultaneously interpreted and documented the conversation.
Information then continued through a fragmented environment of adjuster notes, scanned documents, email attachments and legacy claims systems.
Claims handlers spent significant time reconciling those sources, identifying missing information and converting unstructured descriptions into records suitable for downstream processing.
Fraud assessment presented a related challenge. Potentially suspicious characteristics were often identified later in the claims lifecycle rather than being evaluated systematically when a claim first entered the organization.
That reduced the insurer’s ability to distinguish routine claims from cases requiring additional investigation at an early stage.
The challenge was therefore not simply digitizing FNOL forms. It was creating an intelligent intake environment capable of understanding natural conversations, structuring claim information, identifying missing evidence, orchestrating downstream work and assessing risk from the beginning of the claims lifecycle.
How the problem was approached.
USMICRO established a dedicated Offshore Development Center combining conversational AI architects, insurance-domain specialists, data engineers and integration engineers.
The engineering programme began by redesigning FNOL around natural interaction rather than requiring policyholders to navigate a rigid sequence of static fields.
Speech-to-text and natural-language processing services converted customer conversations into machine-readable information while entity-extraction logic identified relevant details such as parties, assets, locations, incident characteristics and supporting documentation.
Large-language-model capabilities were incorporated where appropriate to summarize complex claim narratives and help identify missing or inconsistent information.
Structured claims data was then passed through governed workflow services into core policy and claims environments.
Fraud-risk scoring was introduced earlier in the process so anomalous or higher-risk submissions could be routed for additional investigation without forcing every claim through the same level of manual review.
The ODC also provided continuing capacity for model refinement, prompt governance, exception handling, security controls and integration changes as claims patterns and operating requirements evolved.
What changed in the technology environment.
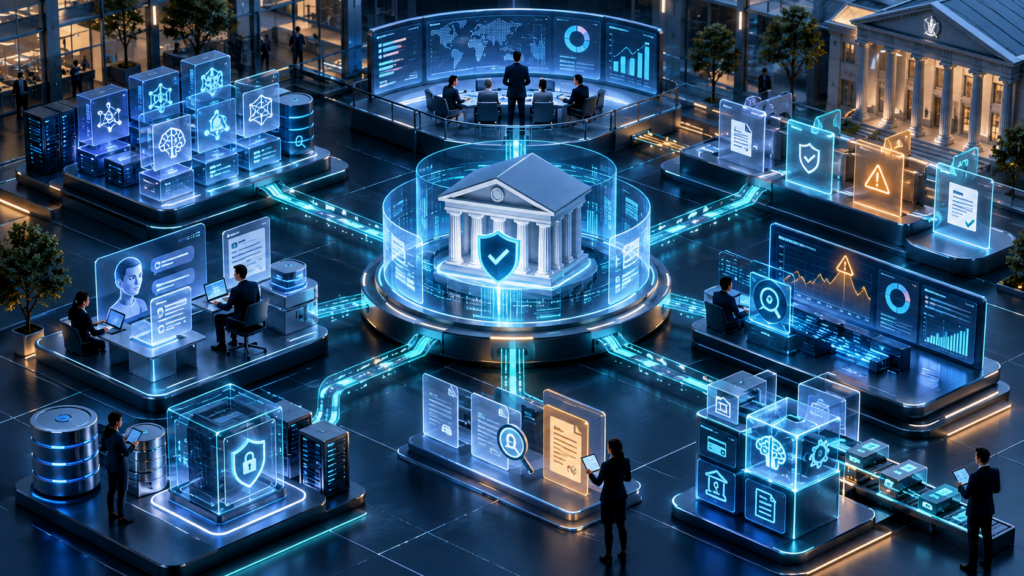
USMICRO introduced a claims-intelligence architecture spanning voice interaction, language processing, document intelligence, workflow orchestration, fraud-risk assessment and core insurance integration.
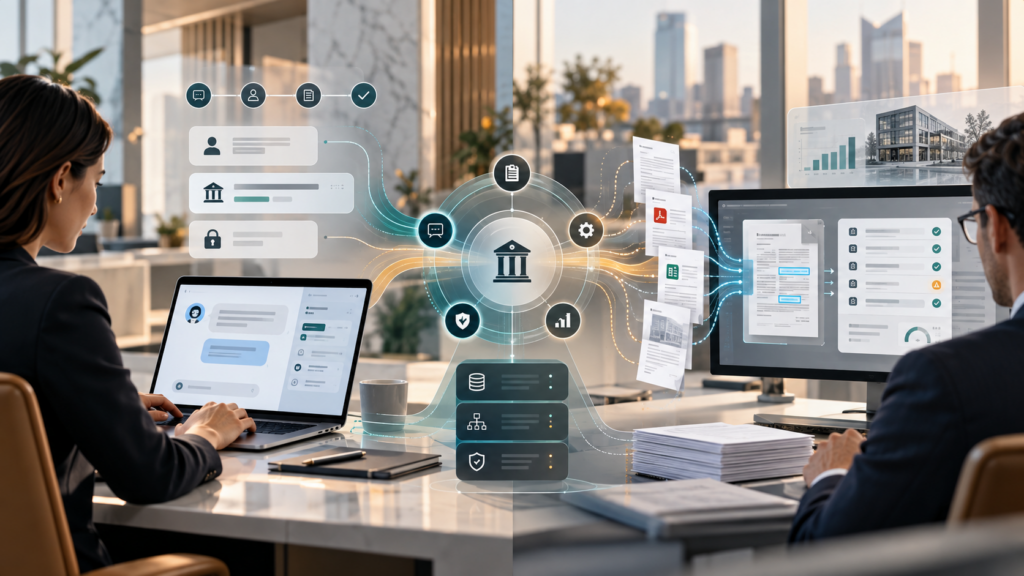
Speech-to-text services converted voice interactions into structured transcripts, while NLP and NLU components extracted intent, entities, urgency and relevant claim context.
LLM-based summarization services transformed longer conversations into concise claim narratives and helped identify information or documentation still required before downstream processing.
Event-driven microservices converted extracted information into structured claims events and routed them into core policy and claims platforms through governed integration services.
Fraud-scoring pipelines evaluated available claim characteristics during intake so higher-risk or anomalous submissions could be surfaced earlier for investigation.
Validation and orchestration layers coordinated documentation requirements, workflow states and human-review exceptions rather than allowing uncertain information to pass directly through automated processing.
Zero Trust access patterns, encryption and governed model controls protected sensitive policyholder and claims information across the workflow.
The architectural shift was therefore from scripted FNOL, unstructured notes and late-stage fraud review toward conversational intake, structured claims intelligence, event-driven orchestration and earlier risk assessment.
What can be credibly demonstrated.
The new claims environment created a more natural and structured entry point into the claims lifecycle.
Policyholders could describe an incident conversationally while the platform converted relevant information into structured claim records rather than relying entirely on manual transcription.
Claims teams received more organized intake information, summarized narratives and clearer indications of missing evidence, reducing the administrative work required before substantive claim evaluation could begin.
Event-driven integration also allowed structured information to move more consistently into core claims environments instead of being repeatedly reconstructed from notes, email and attachments.
Introducing fraud-risk assessment during intake created an earlier opportunity to identify potentially anomalous claims and route them toward appropriate investigation.
Adjusters and claims professionals could therefore spend more time on evaluation, judgment and customer support rather than basic transcription and information reconciliation.
Most importantly, FNOL became the beginning of an intelligent claims workflow rather than merely a manual data-capture stage.